Private health insurance in Wyoming
The real 2026–2027 numbers for Wyoming, who qualifies for help, and when a private, medically-underwritten plan beats paying full Marketplace price — explained honestly by an agent licensed in Wyoming.
The Wyoming marketplace in 2026
Wyoming shops on HealthCare.gov and has the second-most-expensive individual coverage in America: a $1,090 monthly benchmark for a 40-year-old — 74% above the national average — with just two carriers (Blue Cross Blue Shield of Wyoming and UnitedHealthcare) after Mountain Health CO-OP’s exit. Insurers filed another 11.3% for 2027, projecting roughly $1,213.
Wyoming has not expanded Medicaid — the legislature has declined repeatedly — so low-income adults can fall into the coverage gap with neither Medicaid nor subsidies. And above the 400% cliff, Wyomingites face four-figure monthly premiums with two carriers’ worth of “competition.”
Where private plans fit in Wyoming
Ranchers, outfitters, energy contractors, and every other self-employed Wyomingite pays the second-highest health insurance prices in America for the privilege of two choices. If you’re healthy and above the cliff, underwritten private pricing — which ignores Wyoming’s tiny, expensive risk pool — is the closest thing to a real market you’ll find here.
The honest tradeoff, same as everywhere: private plans use medical underwriting. They price on your age and health, which is exactly why healthy applicants often pay less — and why they are the wrong answer if you manage an ongoing condition, take costly prescriptions, are pregnant, or are mid-treatment. In those cases guaranteed-issue ACA coverage protects you in ways no underwritten plan can, and we will tell you so on the first call. Run your own subsidy numbers with our 2027 subsidy calculator or see how Wyoming compares on the state premium map.
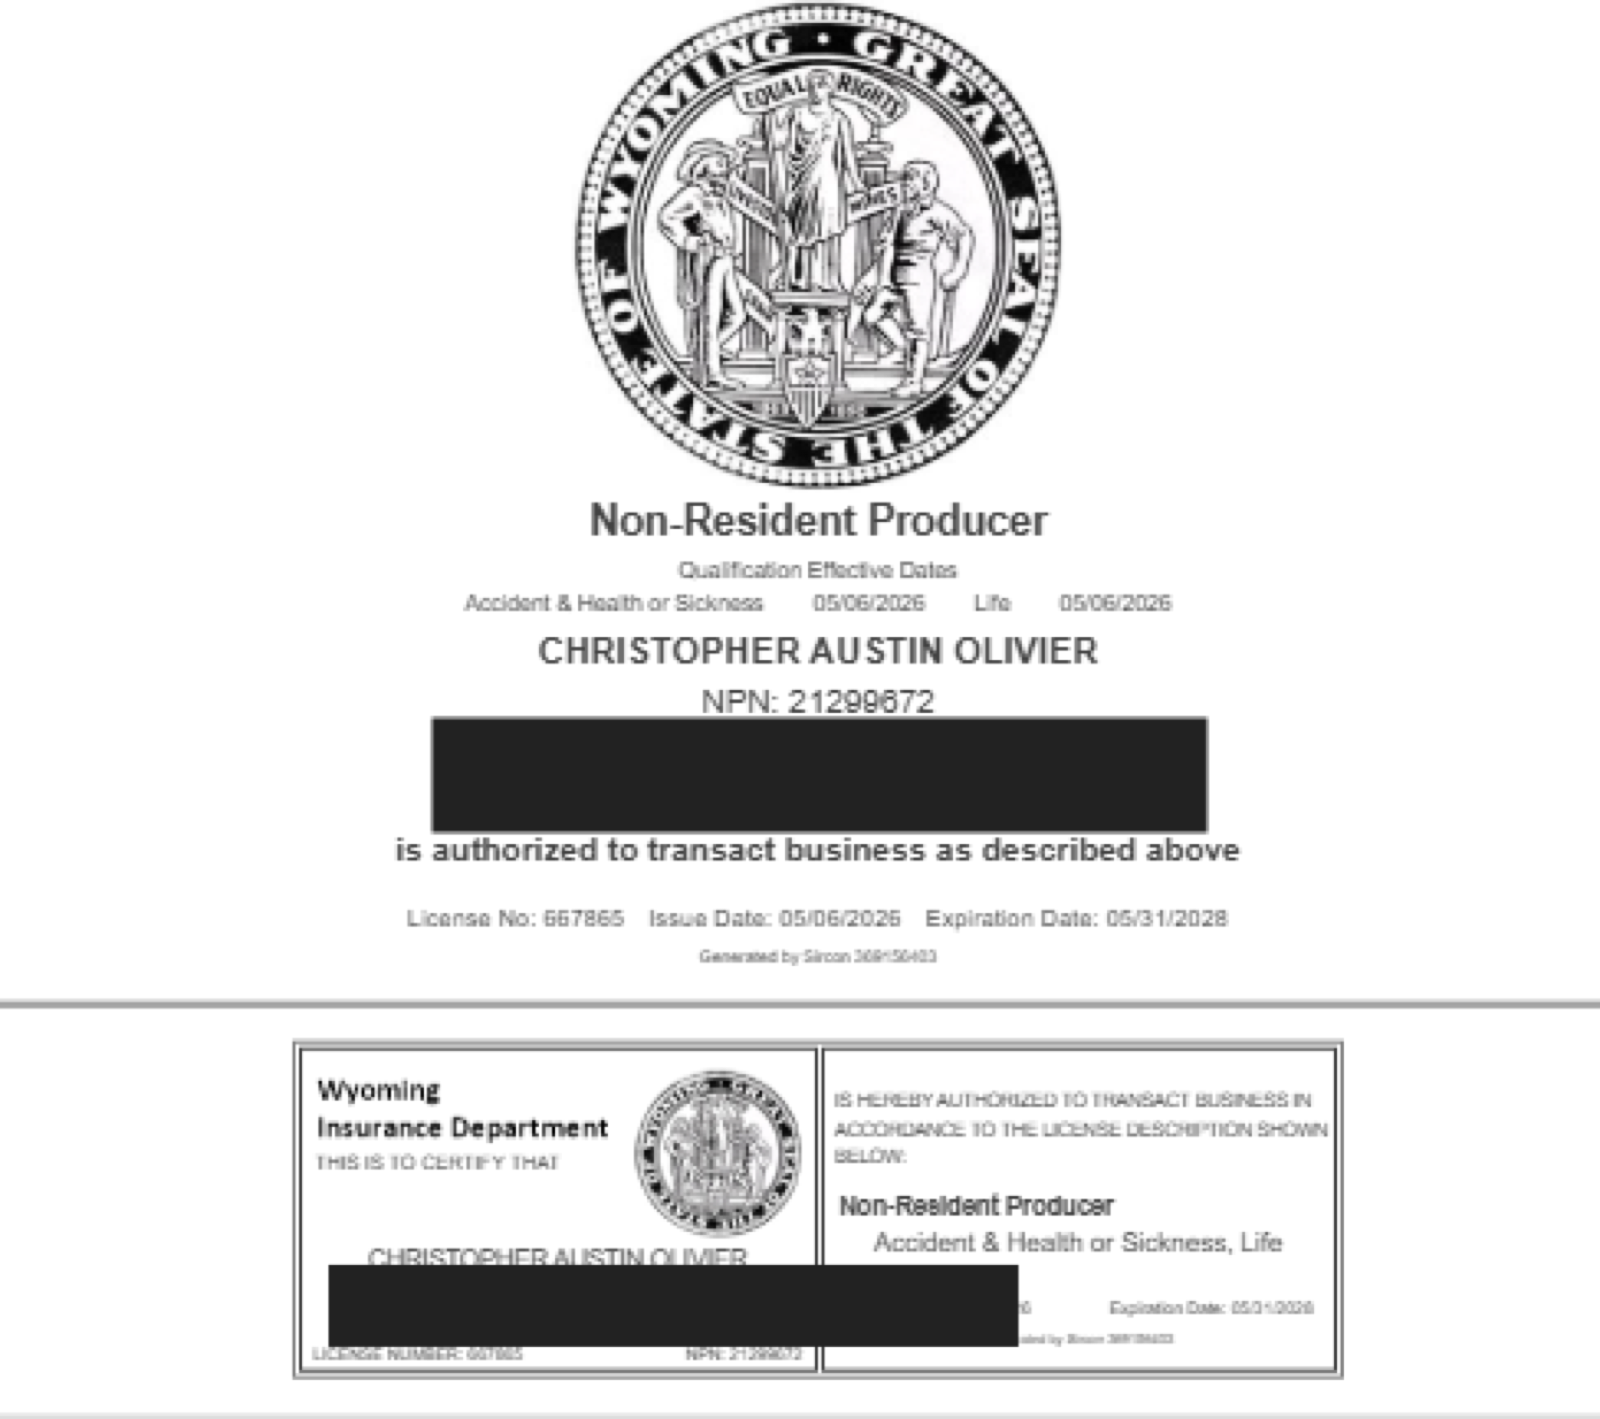
Christopher “Austin” Olivier is licensed in Wyoming under NPN #21299672. Check it against state records through the Wyoming Department of Insurance — official license lookup ↗ — or view every state license on our About page.
Wyoming questions we hear most
Wyoming has the second-highest full-price individual coverage in the country - a published 2026 benchmark of $1,090 a month for a single 40-year-old (KFF). A tiny risk pool spread across a huge rural state with only two carriers does that. Subsidized households are insulated; above the cliff, it's the full four-figure bill.
Through the federal marketplace at HealthCare.gov. Open enrollment for 2027 opens November 1, 2026. Two carriers participate: BCBS of Wyoming and UnitedHealthcare.
No - the legislature has repeatedly declined expansion, so low-income adults can fall into the coverage gap with no Medicaid and no subsidy. If your income is near the poverty line, get a careful eligibility check before assuming anything.
Yes. Christopher A. Olivier holds a Wyoming insurance license (NPN #21299672). Verify it via the Wyoming Department of Insurance consumer page at doi.wyo.gov (agent lookup), and see the certificate posted on this page.
See your real Wyoming options
Free 15-minute comparison with a Wyoming-licensed advisor. No pressure, no obligation — and if the Marketplace is your better deal, we’ll say so.
Sources: KFF benchmark premium data ↗; healthinsurance.org Wyoming marketplace guide ↗; CMS state marketplace list ↗; KFF Medicaid expansion tracker ↗. Educational content, not a quote or offer of coverage. Private plans are medically underwritten and typically exclude pre-existing conditions.